Becoming your own boss rarely fails because of the dream. It usually fails because you budget for the launch and ignore the carry cost of staying alive long enough to build steady revenue.
If you’re weighing self-employment, you need a hard-number view of what you’re replacing, what you’re adding, and what stops being someone else’s problem the moment you leave payroll. This article shows you where the money goes, what most new owners miss, and how to estimate your real runway before you make the jump.
What Does “The Real Cost” Of Becoming Your Own Boss Actually Include?
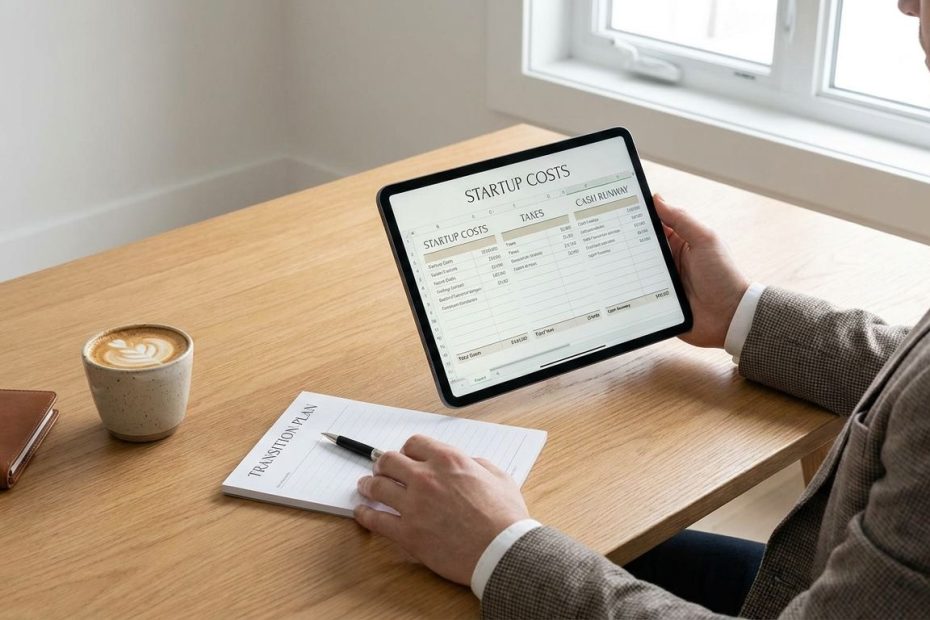
When you leave a job and start working for yourself, your costs split into four buckets: startup expenses, monthly operating costs, taxes and benefits, and opportunity cost. Most people focus on the first bucket because it feels tangible. Filing fees, a website, a laptop, a logo, maybe a desk. Those are visible, easy to price, and easy to overvalue.
The bigger issue is what follows after launch. You now carry recurring software bills, payment processing fees, bookkeeping, marketing spend, insurance, replacement equipment, tax reserves, and uneven cash flow. If revenue comes in late, or not at all for a stretch, every one of those bills still lands. That’s where the real cost shows up.
You also need to factor in what employment used to hide from you. An employer used to cover part of your Social Security and Medicare taxes, absorb part of your health insurance cost, manage payroll systems, and give you paid time off. Once you become self-employed, those costs don’t disappear. They move onto your side of the ledger, and they hit your cash position faster than most new owners expect.
How Much Money Do You Need To Start Your Own Business?
The honest answer depends on what you’re building. A solo service business can often start in the low thousands, while a retail or manufacturing business can run into six figures once inventory, equipment, space, and compliance get involved. That gap matters because too many people use startup stories from freelancers to judge what it will cost to open a store, launch a product line, or run a physical operation.
If you’re starting a service business, your first expenses are usually business registration, a domain name, basic branding, invoicing software, bookkeeping software, insurance, a simple website, and a cash reserve. You may already own the laptop and phone, which lowers your setup bill. That makes the barrier feel manageable, and in many cases it is. Still, low startup cost does not mean low risk. It often means your real risk sits in income inconsistency rather than equipment purchases.
If you’re starting an online business, the cost picture changes again. You may avoid rent and heavy equipment, but you pick up transaction fees, advertising tests, email software, site apps, customer service tools, shipping materials, and return-related costs. That stack tends to grow one monthly charge at a time. A lot of owners don’t feel the weight until they review three months of statements and realize the business is leaking money through small subscriptions.
If you’re opening a retail, food, product, or inventory-heavy business, startup cash needs jump fast. Lease deposits, permits, fixtures, equipment, point-of-sale systems, shelving, packaging, opening inventory, and payroll reserves can burn through a budget before the first sale. In those businesses, underfunding is one of the quickest ways to lose control early. You don’t just need enough to open. You need enough to survive the slow opening phase without making panicked decisions.
What Startup Costs Do Most New Business Owners Underestimate?
Most new owners underestimate boring expenses. They price the visible pieces and ignore the maintenance layer underneath them. You’ll see this all the time: someone budgets for a website but not for hosting, plugins, editing tools, email delivery, image libraries, form software, analytics, and the occasional contractor needed to fix what breaks.
Administrative costs are another blind spot. Business registration is not the end of compliance. Depending on your state and structure, you may have annual reports, renewal fees, registered agent service, local licensing costs, and accounting work tied to taxes. None of these items feels dramatic on its own. Added together, they become a recurring drain that narrows your margin.
Marketing is usually underfunded too. New owners often assume word of mouth will carry them, or they treat advertising as optional. That’s a mistake. If your business depends on finding clients or customers consistently, you need a lead generation budget, whether that’s search engine optimization, ads, email, local outreach, referral systems, printed materials, or a sales tool stack. Customer acquisition has a price, and if you don’t assign it early, it shows up later as desperation.
The final underpriced item is time. Administrative work, follow-up, proposals, invoicing, revisions, scheduling, bookkeeping, and customer support can consume hours you thought would be billable. If you charge for only twenty hours a week but work fifty, your effective rate collapses. That gap is one of the most expensive hidden costs in self-employment.
How Much Does It Cost To Form A Business Legally?
The legal setup cost depends on your state, your business structure, and how much help you pay for. A limited liability company, or LLC, often looks cheap at first because the filing fee alone may fall into a modest range. Still, the filing fee is just the entry point. You may also pay for name reservation, a registered agent, state reporting, business licenses, and professional help if you don’t want to file on your own.
This is where many owners get sloppy. They hear one number from a friend, search one state-specific fee online, and assume the matter is closed. It isn’t. The upfront filing may be manageable, but annual maintenance can change the economics. If your state has recurring fees or reporting requirements, that cost belongs in your fixed annual budget from day one.
You should also separate “legally formed” from “operationally ready.” Forming the company does not cover contracts, bookkeeping setup, invoicing workflows, sales tax handling where applicable, banking, merchant processing, or insurance. Owners who stop planning after registration end up with a legal shell and no working system behind it. That’s not a business yet. That’s paperwork.
What Taxes Hit You Hardest When You Work For Yourself?
The tax shock usually starts with self-employment tax. In the United States, self-employment tax is generally 15.3 percent and covers Social Security and Medicare taxes. If you’ve spent years as an employee, you’re used to seeing only your side of that split on a pay stub. Once you’re self-employed, you effectively carry both shares through self-employment tax.
That number catches people off guard because they compare business income to old salary income without adjusting for tax structure. A new owner looks at a freelance contract, sees a gross monthly number that seems close to an old paycheck, and assumes the switch works. It doesn’t work that way. Gross revenue is not take-home pay, and net profit is not spendable cash until you reserve money for taxes.
You also need to plan for federal income tax, state income tax where applicable, and quarterly estimated payments. Miss those estimates and the problem compounds. You’re no longer just paying what you owe. You may also be dealing with penalties, cash strain, and the stress of trying to catch up from operating income that should have stayed inside the business.
A disciplined owner treats taxes as a line item every month, not a surprise every quarter. That means setting aside a percentage from every payment received, keeping clean books, and reviewing profit with reality instead of optimism. If you don’t do that, the business can look healthy right up until tax season exposes the truth.
How Much Does Health Insurance Really Add To The Cost?
Health insurance is one of the clearest examples of a cost that employees underestimate because the full price was never visible. When you buy your own coverage, you see the premium directly. For self-employed people, that can mean hundreds of dollars a month even before you think about deductibles, coinsurance, prescriptions, or family coverage.
You also need to separate sticker price from actual out-of-pocket cost. Marketplace plans may be reduced by premium tax credits depending on your income and household details, which can change the amount you actually pay. Still, if you’re leaving a job with subsidized employer coverage, you need to compare what you paid as an employee with the full replacement cost you may now face on your own.
This is where people make bad math look good. They say, “I only need to replace my salary.” No, you need to replace your compensation package. Your paycheck was just one part of it. If the old job came with employer-supported health coverage, paid time off, retirement matching, and payroll tax support, your self-employed income target has to cover all of that. Otherwise, you’re measuring freedom against the wrong baseline.
If you have a spouse, children, or ongoing medical needs, health insurance planning moves from line item to decision-maker. A business that looks viable without insurance may look far tighter once real family coverage enters the budget. That doesn’t mean the move is wrong. It means your threshold for “enough income” needs to be honest.
Why Is Cash Runway More Important Than Startup Budget?
Startup budget gets the attention because it answers the emotional question: can you begin? Cash runway answers the business question: can you survive? Those are not the same thing. You can start a business with very little money in some categories, but you cannot stay in business if your personal and operating reserves run dry before revenue stabilizes.
A useful planning standard is to calculate startup costs and then map at least one year of monthly expenses. That includes business costs and personal living costs if the business is expected to support you. A lot of new owners stop at three months of runway because six or twelve months feels uncomfortable to fund. The issue is that business growth rarely respects your preferred timeline.
Runway matters because revenue is rarely smooth in the early phase. Clients delay. Sales cycles stretch. Marketing channels underperform. Referrals come in bursts. Payment terms work against you. If you need immediate income, you’re forced into short-term choices that can damage pricing, positioning, and client quality. Owners with runway can say no to bad-fit work and fix problems before they become fatal.
The simplest way to think about runway is this: it buys decision quality. If your savings can cover your business burn and personal obligations long enough to learn, adjust, and sell properly, you have room to operate like an owner. If not, the business starts owning you.
What Monthly Costs Keep Draining A New Business?
Monthly costs are where your business gets tested. The recurring bills often look harmless one by one: bookkeeping software, file storage, email marketing, scheduling tools, domain renewals, design apps, customer service platforms, payment processing, ad spend, internet, phone, and insurance. Still, recurring software creep is real, and it eats margin quietly.
Payment processing deserves extra attention. If you accept cards or online payments, you’re giving up a percentage of every transaction. On healthy margins, that may be manageable. On thinner offers, it can reshape your pricing model. Owners who ignore transaction fees often believe they’re profitable until reconciled statements show what the processor took off the top.
Then there’s labor, including part-time help. You may start alone, but the moment fulfillment, support, editing, design, or admin work starts stealing selling time, you’ll consider outsourcing. That can be smart. It can also wreck cash flow if you hire before the revenue base is stable. The point is not to avoid help. The point is to time it with discipline and tie it to return, not relief.
Rent and utilities may not hit every business, but when they do, they change the risk level fast. Physical overhead removes flexibility. Once you sign a lease, your margin doesn’t just need to support growth. It needs to support commitment. That’s why many seasoned operators stay lean longer than beginners expect. Flexibility has monetary value.
What Is The Opportunity Cost Of Leaving A Job?
Opportunity cost is the money you stop receiving or the financial ground you give up when you leave employment. Salary is the obvious piece. The less obvious pieces are employer-paid benefits, retirement match, paid vacation, paid sick leave, equipment, training, and the stability of predictable pay cycles.
You should also account for the ramp period when your business may produce less income than your job. If you leave a steady paycheck for uncertain revenue, the difference between those two income streams is part of the cost. This matters even more if you carry debt, dependents, or fixed household obligations that don’t shrink just because you’re excited about the switch.
There’s another layer people don’t like to price: unpaid labor. When you become your own boss, a slice of your week shifts into non-billable work. Sales calls, email cleanup, proposal writing, tax prep, account management, follow-ups, system setup, and customer service all take time. If that work consumes ten hours a week and your billable rate is strong, you’re giving up meaningful earning capacity to keep the machine running.
That’s not a reason to stay employed. It’s a reason to compare the move against a full compensation picture instead of a fantasy version of independence. If your old job paid less than you wanted but covered expensive benefits and gave you stable hours, the replacement target for self-employment is often higher than you think.
Do Clients Become Your New Boss?
In practical terms, yes, they often do. You may lose a manager, but you gain clients, customers, vendors, regulators, deadlines, payment terms, reviews, and market pressure. If you serve several clients at once, you don’t have one boss anymore. You have multiple people with competing expectations and varying levels of urgency.
This matters financially because client behavior shapes cash flow and workload. A demanding client can force revisions, calls, rush work, and schedule changes that reduce your capacity to sell or deliver for others. A late-paying client can create stress that has nothing to do with profit on paper. Revenue quality matters as much as revenue quantity.
That’s why pricing, contracts, payment terms, and scope control are not side issues. They’re financial controls. If you let clients dictate process, your margins erode through unbilled labor and operational drag. Owners who stay profitable learn to screen clients, define deliverables, invoice clearly, and enforce boundaries without apology.
Being your own boss does give you control over direction, offers, positioning, and standards. That part is real. What changes is the source of pressure. It doesn’t disappear. It becomes distributed, and if you don’t build systems around it, your calendar fills up with other people’s priorities.
How Do You Calculate Your Real Number Before You Quit?
Start with personal monthly expenses. Include housing, food, transportation, debt payments, utilities, child care, insurance, savings goals, and anything else that leaves your bank account on a regular cycle. Then add business operating costs, even if some feel small. This gives you a base monthly burn number that reflects your actual life.
From there, add tax reserves and benefits replacement. If you’ll pay for your own health insurance, include that. If you’re losing retirement matching, decide whether you’ll replace it and at what amount. Then build in self-employment tax and income tax reserves instead of pretending net receipts are spendable.
Now estimate startup costs separately. Legal formation, equipment, software setup, branding, website, inventory if needed, deposits, and any launch-related contractor help belong here. Once you have that number, add runway. If your monthly burn is real and your startup budget is accurate, you can estimate how much cash you need to open without forcing the business to perform too soon.
Then pressure-test the plan. What happens if revenue takes twice as long to ramp? What happens if your best client disappears? What happens if health insurance costs more than expected or your ad tests fail? If the model breaks under mild stress, the issue is not ambition. The issue is timing, savings, or cost structure.
What Can You Do To Lower The Cost Without Crippling The Business?
Start lean, but don’t start sloppy. There’s a difference. You can avoid expensive branding packages, office space, fancy software stacks, and unnecessary subscriptions early on. You cannot avoid clean bookkeeping, legal setup, tax planning, clear offers, and a sales process. Cutting vanity costs is smart. Cutting control systems is expensive later.
Use staged spending. Buy what the business needs for the current revenue phase, not the business identity you want to perform online. Many owners build for scale before they’ve proven demand. That usually means paying for tools, contractors, and systems that sit half-used while cash gets tighter.
You should also protect margin through simple operating rules. Keep subscriptions on review, separate business and personal banking, reserve money for taxes from each payment, tighten invoicing terms, and track customer acquisition cost early. If a recurring expense doesn’t produce revenue, save time, or reduce risk, it needs scrutiny.
The best cost control move may be keeping your job longer while you validate the business. That’s not glamorous, but it works. If you can build clients, repeat sales, or proof of demand before you depend on the income, you reduce pressure and improve your odds. There’s no trophy for quitting too early.
What Is The Real Cost Of Becoming Your Own Boss?
- Startup costs include legal setup, tools, equipment, branding, and launch expenses.
- Ongoing costs include software, marketing, insurance, taxes, and admin time.
- You also replace employee benefits, steady income, and payroll tax support.
- Your true number is startup budget + monthly burn + cash runway.
Build Your Exit Plan Like An Owner, Not A Dreamer
If you want to become your own boss, price the move with discipline before you romanticize it. Your real cost is not just what it takes to launch, it’s what it takes to operate, pay yourself, cover taxes, replace benefits, and survive a slow ramp without panic. Once you understand those numbers, you stop asking whether self-employment sounds freeing and start asking whether your model can carry the weight. That’s the right question. Answer it honestly, and you’ll make better decisions about timing, savings, pricing, and the kind of business you’re actually ready to build.

Olivier Gillier is a global investment strategist and co-founder of RioBlanco Capital LLC, with over 20 years of experience in wealth management and international markets. A former Senior Vice President at Merrill Lynch, he now focuses on private equity, cross-border finance, and philanthropic initiatives worldwide.