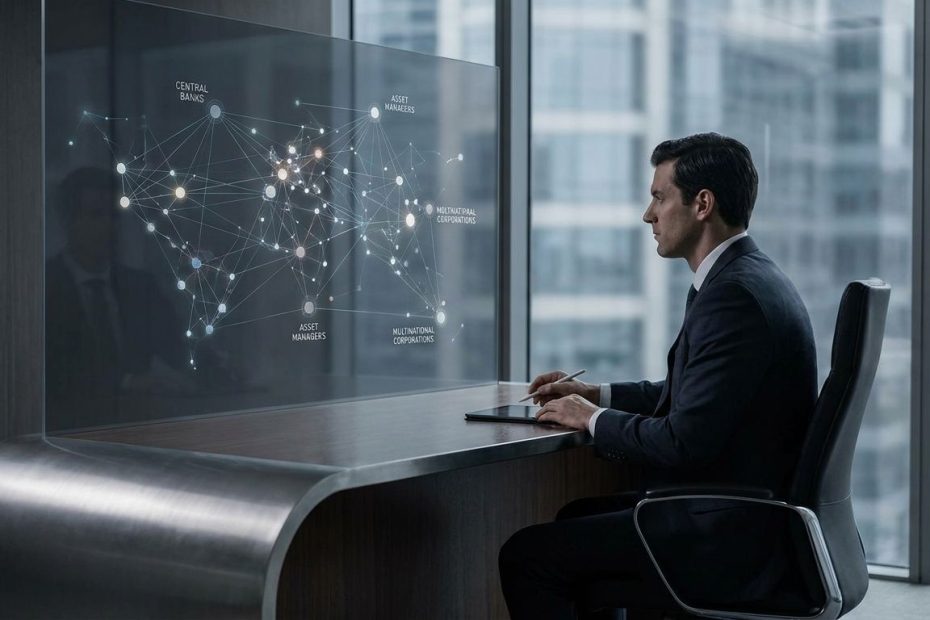
Global financial control is shared, not owned by one person, one bank, or one government. The system runs through overlapping power centers: reserve currencies, central banks, commercial banks, asset managers, governments, payment networks, rule-setting bodies, and markets.
You’re usually asking this question because the system feels too large to be accidental and too coordinated to be random. The better answer is less cinematic and more useful: power shifts depending on the situation. In calm periods, markets and private capital steer money flows; in stress periods, central banks and governments can suddenly become the strongest actors in the room.
Who Really Controls The Global Financial System?
No single entity controls the global financial system. Control is distributed across institutions that create money, lend money, price risk, enforce rules, move payments, and decide which currencies people trust.
If you’re looking for one hidden switchboard, you’ll miss how financial power actually works. A central bank can set interest rates, yet bond investors can punish a government by demanding higher yields. A commercial bank can move huge sums, yet regulators can force it to hold more capital. A government can impose sanctions, yet markets can raise the cost of those choices through weaker currencies, lower investment, and higher borrowing costs.
The system acts less like a pyramid and more like a web of pressure points. The strongest player changes with the problem: liquidity stress, inflation, banking panic, sovereign debt trouble, currency collapse, or geopolitical conflict. That’s why global financial control is best understood as situational power rather than permanent command.
Why Does The U.S. Dollar Shape Global Financial Control?
The United States dollar shapes global financial control because it is the main reserve currency, the dominant currency in foreign exchange trading, and a major currency for international debt. That gives the United States and the Federal Reserve unusual reach, even outside U.S. borders.
The dollar accounts for 58.9% of allocated foreign exchange reserves, which means central banks around the world hold large dollar balances for stability, trade, and crisis defense. Around 60% of international debt securities are denominated in dollars, so borrowers outside the United States often depend on access to dollar funding. The dollar is also involved in 88% of foreign exchange transactions, which makes it the main currency through which many global trades are priced and settled.
This does not mean the United States can dictate every financial outcome. It does mean U.S. interest rates, dollar liquidity, and trust in U.S. financial institutions ripple through emerging markets, corporate debt, trade finance, and commodity pricing. When the dollar rises, countries with dollar debt can face higher repayment costs; when dollar funding dries up, banks and companies far from New York can feel the squeeze.
Is The Federal Reserve The World’s De Facto Central Bank?
The Federal Reserve is not legally the world’s central bank, but it often behaves like the main provider of emergency dollar liquidity. Its power comes from the dollar’s role, not from a formal global mandate.
The Federal Reserve operates permanent central bank liquidity swap lines with the European Central Bank (ECB), Bank of Japan (BoJ), Bank of England (BoE), Bank of Canada (BoC), and Swiss National Bank (SNB). These swap lines let foreign central banks provide dollars to banks in their own jurisdictions when dollar funding becomes strained. The Fed can also open temporary lines with other central banks during market stress.
That gives the Fed a unique place in global financial governance. A rate decision in Washington can affect mortgage costs in the United States, debt costs in emerging markets, corporate refinancing in Europe, and capital flows across Asia. Still, the Fed’s formal job is domestic: price stability and maximum employment in the United States. The global effect comes from dollar dependence, not from a world-government role.
How Do Other Central Banks Coordinate When Stress Hits?
Other central banks coordinate through swap lines, shared committees, regulatory standards, and emergency communication channels. They can act fast, but they usually cannot replace the dollar system on their own.
The Bank for International Settlements (BIS) is central to that coordination. It is owned by 63 central banks, acts as a bank for central banks, and hosts committees that shape banking rules, including the Basel Committee on Banking Supervision. That matters because the biggest banks operate across borders, so national rules need enough alignment to stop weak points from spreading through the system.
The European Central Bank, Bank of Japan, Bank of England, and other major central banks can create their own currencies and support their domestic financial systems. Their limits appear when banks, companies, or governments need dollars rather than euros, yen, or pounds. In those moments, coordination with the Federal Reserve becomes a practical necessity rather than a courtesy.
How Do Governments, Sanctions, And Payment Networks Rewire Money Flows?
Governments influence global finance through law, taxation, borrowing, capital controls, bank regulation, sanctions, and access to payment networks. They do not need to own the financial system to redirect it.
Sanctions are one of the clearest examples of state power over finance. A government can restrict access to banks, block assets, limit transactions, or pressure companies to leave a market. When the target relies on dollar clearing, global banks, or cross-border payment channels, those restrictions can become difficult to avoid.
The Society for Worldwide Interbank Financial Telecommunication (SWIFT) is often misunderstood here. SWIFT is a messaging network for financial institutions, not a world central bank and not a pile of money. Its governance is overseen by Group of Ten (G-10) central banks, led by the National Bank of Belgium. That means payment infrastructure sits between private banks, central bank oversight, and government pressure.
Do Big Banks, Asset Managers, And Shadow Banks Control Money Flows?
Big banks and asset managers influence money flows, but they do not control them alone. Their power comes from scale, client networks, balance sheets, lending relationships, and the ability to move capital across markets.
BlackRock had $10.47 trillion in assets under management, making it the world’s largest asset manager. That does not mean it owns all of that money; assets under management are mostly client assets managed under mandates. Still, when a firm of that size allocates money across stocks, bonds, exchange-traded funds, and institutional portfolios, its decisions can affect prices, liquidity, and corporate financing conditions.
JPMorgan Chase, with about $4.0 trillion in total assets, shows a different kind of private power. Large banks sit inside payment systems, credit markets, treasury services, derivatives, custody, and consumer finance. Shadow banking adds another layer through money market funds, hedge funds, private credit, and other non-bank lenders. These institutions can expand credit fast during good times, then pull back when risk rises, which can turn a routine slowdown into a funding crunch.
What Do The International Monetary Fund, World Bank, And Bank For International Settlements Actually Do?
The International Monetary Fund (IMF), World Bank, and Bank for International Settlements do not run global finance like executives run a company. They shape rules, provide funding, coordinate policy, and set standards that national governments and financial institutions often follow.
The International Monetary Fund has 190 member countries and roughly $1 trillion in lending capacity. Its main role is financial stability: monitoring economies, lending to countries in trouble, and attaching policy conditions to support packages. That conditionality is why the IMF attracts distrust; countries that need rescue funding often face spending cuts, reforms, or other policy changes as part of the deal.
The World Bank has a different role. It focuses on development and long-term lending, with total commitments around $73 billion. The Financial Stability Board (FSB), hosted at the BIS, coordinates national financial authorities and develops rules for systemically important financial institutions, often called too-big-to-fail firms. These bodies do not command markets by decree, but their standards can shape bank capital, crisis planning, and cross-border supervision.
Who Enforces Discipline When No One Is Fully In Charge?
Financial markets enforce discipline by repricing risk. Bond yields, currency values, stock prices, and funding spreads can force banks and governments to adjust long before any global authority steps in.
The foreign exchange market has about $7.5 trillion in daily turnover, making it the largest and most liquid financial market. If investors lose trust in a country’s currency, capital can leave quickly and the exchange rate can fall. That can make imports costlier, raise inflation pressure, and increase the burden of foreign-currency debt.
Bond markets can be just as forceful. When investors demand higher yields to hold government debt, borrowing costs rise and fiscal choices narrow. This is often described as the “bond vigilante” effect: markets do not pass laws, yet they can make certain policies expensive. That’s why governments may appear powerful on paper and constrained in practice.
Who Controls Global Finance?
- Power is decentralized.
- The U.S. dollar gives the Federal Reserve extra reach.
- Central banks coordinate in crises.
- Banks, governments, and markets all shape control.
What To Watch When The System Breaks
The real answer to global financial control is not a name; it’s a chain of pressure. Watch the dollar, central bank swap lines, bond yields, payment access, bank funding, and cross-border capital flows. Those signals tell you who has leverage at that moment. In a crisis, the Federal Reserve can become the main source of dollar relief, governments can freeze or redirect money flows, and markets can punish weak balance sheets within hours. The system has no single captain, which makes it harder to control, harder to predict, and far more fragile than it looks from the outside.
References
- International Monetary Fund Currency Composition of Official Foreign Exchange Reserves
- Bank for International Settlements International Debt Securities Statistics
- Bank for International Settlements Triennial Central Bank Survey
- Federal Reserve Central Bank Liquidity Swap Lines
- Bank for International Settlements About Page
- SWIFT Organization And Governance
- BlackRock Investor Relations Financial Statements
- JPMorgan Chase Investor Relations
- McKinsey Global Wealth Report
- International Monetary Fund Lending Factsheet
- World Bank Annual Report
- Financial Stability Board About Page
- Reuters Analysis On Bond Vigilantes.

Olivier Gillier is a global investment strategist and co-founder of RioBlanco Capital LLC, with over 20 years of experience in wealth management and international markets. A former Senior Vice President at Merrill Lynch, he now focuses on private equity, cross-border finance, and philanthropic initiatives worldwide.