Banks usually fail on timing before they fail on total value. You can have a bank with plenty of assets on paper, yet it still runs short of cash if too many depositors want their money at once and those assets can’t be turned into spendable funds fast enough.
If you want to understand bank stress without the usual fog, focus on one distinction: liquidity is about paying today, solvency is about surviving overall. Once you lock that in, the rest of the story makes sense, from classic bank runs to Silicon Valley Bank, deposit insurance, Federal Reserve backstops, and why “the bank has assets” does not mean “the bank can meet every withdrawal right now.”
Why Can A Bank Have Plenty Of Assets But Still Run Out Of Cash?
You need to separate a bank’s assets from its immediate liquidity. Assets include loans, mortgage-backed securities, Treasury securities, business credit lines, and other claims that pay over time. Cash for withdrawal demands is different. That means vault cash, reserve balances, and funding the bank can access quickly enough to settle outgoing payments the same day.
A commercial bank’s business model depends on turning short-term funding into longer-term earning assets. Depositors can ask for money on demand, but the bank does not keep every dollar sitting idle. It lends part of those funds out or invests them in securities that may be safe over time but cannot always be sold fast at full value. That gap between payable now and collectible later is the reason a bank can run short of cash before it runs out of assets.
The Richmond Federal Reserve explains this plainly: banking is maturity transformation, often described as borrowing short and lending long. That structure helps households and businesses get credit, but it also makes banks vulnerable if too many depositors rush for the exit at once. When withdrawals accelerate, the issue is not whether the bank owns something valuable. The issue is whether it can convert enough of that value into usable cash before confidence breaks.
You see the same logic in every fast-moving bank panic. A loan portfolio may keep producing payments for years. A bond portfolio may still pay in full if held to maturity. None of that solves a same-day funding problem. Banks run out of settlement liquidity first because payment obligations move faster than assets mature.
What Is The Difference Between A Liquidity Problem And A Solvency Problem?
This is where many readers get tripped up. A liquidity problem means the bank cannot raise enough cash quickly enough to meet withdrawals or payment obligations. A solvency problem means the bank’s assets are no longer worth enough to cover what it owes. Those are not the same condition, and a bank can be illiquid without being insolvent.
That said, one problem can turn into the other. The Richmond Federal Reserve notes that a sudden wave of withdrawals can force a bank to sell assets at steep discounts. Those fire-sale losses destroy value. A bank that might have survived if given time can be pushed into failure because it had to liquidate assets too fast and too cheaply. That sequence matters: liquidity stress often arrives first, then realized losses eat into capital.
You should picture this as a speed problem with a balance-sheet consequence. A bank may own long-dated Treasury securities or mortgages that would pay as expected if left alone. If it must sell those holdings today, during stress, it may lock in losses that were only unrealized before. Once capital shrinks, confidence gets worse, counterparties get nervous, depositors move faster, and the squeeze tightens.
That is why bank supervisors, treasury teams, and chief risk officers spend so much time on liquidity ladders, collateral capacity, deposit stability, and funding concentration. Solvency is the long game. Liquidity is the daily survival test.
Why Don’t Banks Just Keep Everyone’s Deposits In Cash?
If a bank held every deposited dollar in cash all the time, it would stop functioning like a bank. You would not get the same credit creation, business lending, mortgage financing, or earnings model. The entire point of banking is to take funds that some depositors do not need today and put them to work in loans and securities that earn over time. That is the tradeoff.
You also need to clear up a common myth: U.S. banks are not required to hold a fixed chunk of transaction deposits as reserves in the way many people still assume. The Federal Reserve states that reserve requirement ratios were reduced to zero percent, effective March 26, 2020. That does not mean banks hold no liquidity. It means liquidity management is handled through a broader mix of cash, reserves, securities, funding plans, collateral management, and regulation rather than a simple old-school reserve ratio rule.
In practice, banks carry buffers, not full cash backing. They hold liquid assets, maintain access to funding markets, pre-position collateral, model runoff risk, and use central bank facilities when needed. That setup works under normal conditions and under many stress conditions. It breaks when withdrawal demand outruns those buffers and access points.
If you want the blunt version, here it is: a bank that keeps all deposits in cash is safe from runs but poor at being a bank. A bank that lends and invests earns a spread and supports the real economy, but it takes liquidity risk. The entire system is built around managing that risk, not eliminating it.
How Does A Bank Run Actually Start?
A bank run starts when depositors decide that waiting is riskier than leaving. The first wave may come from real concerns about losses, poor risk management, or concentrated funding. It may also come from fear that other depositors are about to move first. In banking, expectations can become self-fulfilling with brutal speed.
The Richmond Federal Reserve’s discussion of bank runs gets to the heart of it: depositors know the bank cannot meet the demands of all depositors at one time. If enough people think others are about to withdraw, they rush to withdraw before reserves are depleted. That is the ugly arithmetic of a run. A solvent institution can be pushed into distress if confidence collapses faster than liquidity can be raised.
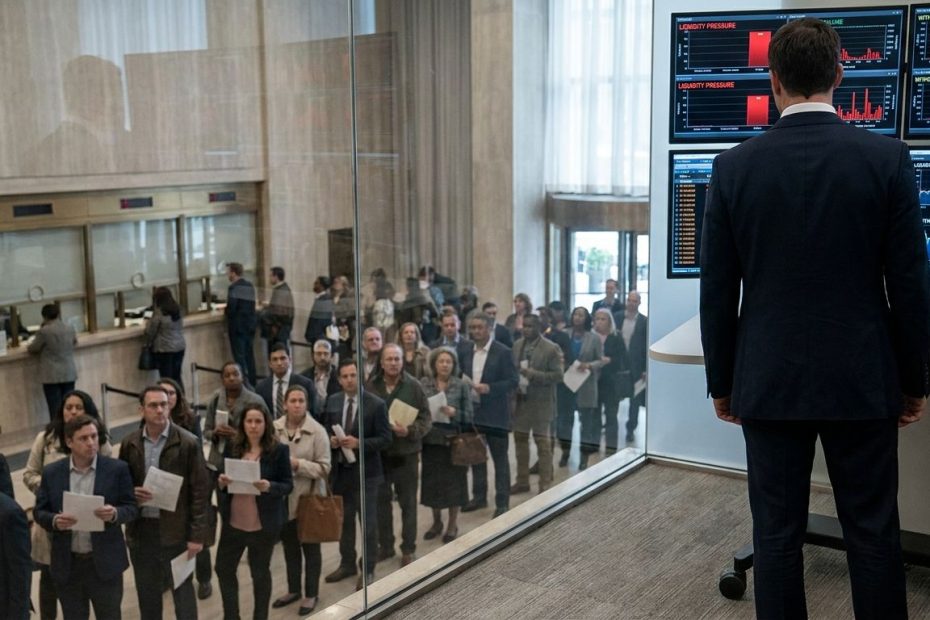
Modern bank runs move faster than the old movie version with lines outside a branch. Corporate treasurers can send large transfers in minutes. Venture investors can tell portfolio companies to move funds right away. Group chats, internal finance teams, online portals, and payment rails compress what once took days into hours. You don’t need a crowd on the sidewalk anymore. You need a concentrated depositor base and a reason to doubt.
Runs are also more likely when a bank’s deposit base is unusually uninsured or concentrated. Large commercial depositors monitor risk differently from retail savers. If they believe there is even a chance they could be trapped, they move fast. No one wants to be the last person still standing when wires stop going out.
What Did Silicon Valley Bank Show About Cash Versus Assets?
Silicon Valley Bank gave the public a clean, painful example of how quickly usable liquidity can vanish. According to testimony summarized by CNBC, customers withdrew $42 billion on March 9, and another $100 billion was expected to leave the next day. That would have totaled about 81 percent of the bank’s deposits over two days. At that speed, the problem is not whether the bank owns assets. The problem is whether cash can be raised before the outgoing wires overwhelm the bank.
The structure of the deposit base made the situation more fragile. S&P Global reported that Silicon Valley Bank had a very high share of uninsured deposits and a very high ratio of loans plus held-to-maturity securities relative to deposits. It also noted that many clients held balances well above the Federal Deposit Insurance Corporation insurance limit. That matters because uninsured depositors have a stronger reason to move early and ask questions later.
You can also see how interest-rate risk and liquidity risk feed each other. Silicon Valley Bank held securities that had lost market value as rates rose. If those securities could have been carried to maturity without stress, the damage might have stayed contained. Once the bank needed cash quickly, sales and borrowing capacity became central. Losses that were manageable in an accounting sense became a threat in a funding sense.
That is the case study you should keep in mind whenever someone says, “But the bank had assets.” Yes, it did. The failure point was that withdrawals outran immediately available liquidity and the bank’s ability to bridge the gap without crippling losses.
How Do Uninsured Deposits Make Runs Faster?
Deposit insurance changes depositor behavior. If your account is clearly within insured limits, you have far less reason to sprint for the exit at the first sign of trouble. If your balance is well above insured coverage, you start thinking like a risk manager. You monitor headlines, capital raises, market chatter, unrealized losses, and counterparty confidence. That shift in behavior matters more than most people realize.
The Federal Deposit Insurance Corporation states that the standard insurance amount is $250,000 per depositor, per insured bank, for each account ownership category. If you are a household saver with balances inside that limit, your incentive to run is reduced. If you are a startup, law firm, fund, or operating company with millions in payroll cash at one institution, your calculation is different.
When a bank’s deposits are concentrated in large, uninsured accounts, the withdrawal profile becomes less stable. Those depositors are often financially sophisticated, operationally connected, and able to move funds with a few approvals. They do not need to visit a branch, wait in line, or break a passbook. One treasury instruction can move millions. If many treasurers act the same way, liquidity pressure spikes fast.
That is one reason deposit mix gets so much attention in bank analysis. Two banks can show similar total deposits, similar asset size, and similar capital ratios. The one with stickier retail deposits will usually be less vulnerable than the one funded by concentrated, uninsured commercial balances that can leave in a flash.
How Do Regulations Like The Liquidity Coverage Ratio And Net Stable Funding Ratio Help?
After the financial crisis, regulators built liquidity rules to reduce run risk and force large banks to carry more dependable buffers. The Liquidity Coverage Ratio requires certain large banks to hold enough High-Quality Liquid Assets to meet net cash outflows over 30 days in a stressed scenario. The Net Stable Funding Ratio pushes banks toward funding structures that are more stable over a longer horizon.
The Congressional Research Service describes the idea cleanly: banks should hold enough liquid assets to match expected stressed outflows, and the weights on assets and funding depend on how liquid or stable they are under pressure. That makes these rules practical guardrails. A Treasury security is treated differently from a thinly traded asset. Sticky retail deposits are treated differently from flight-prone funding.
You should not read these rules as a promise that banks are run-proof. They are designed to improve odds, lower the severity of stress, and force better preparation. They cannot guarantee survival if the depositor base is unusually concentrated, if the speed of outflows crushes the stress model, or if confidence evaporates overnight.
That last point matters more now than it did in an earlier banking era. A thirty-day stress concept is useful. A two-day digital panic can still be lethal. Rules help, but they do not repeal crowd behavior or payment speed.
Why Can’t A Bank Just Borrow Against Its Assets During A Panic?
Sometimes it can, and that is one reason many liquidity events do not become failures. A bank can borrow in private markets, pledge securities, tap secured funding channels, or go to the Federal Reserve’s discount window. That is the good news. The bad news is that borrowing capacity is never infinite, and it gets harder to use under stress if confidence falls or collateral is already tied up.
The Federal Reserve states that the discount window allows depository institutions to borrow from Reserve Banks after executing legal agreements and pledging collateral. It is meant to support liquidity risk management and reduce the need for actions that hurt customers and credit flows. That is the textbook lender-of-last-resort function. Still, every loan must be collateralized, and pledged assets must be available, eligible, and operationally ready.
Collateral management is where many outsiders underestimate the problem. If a bank’s strongest assets are already pledged elsewhere, or if a prior lien limits flexibility, emergency borrowing becomes tighter than it looks from the outside. The Federal Reserve notes that institutions must post collateral before borrowing, and it also points out that other lenders, including Federal Home Loan Banks, may already have claims on assets. In a squeeze, the amount of unencumbered collateral becomes one of the most important numbers on the page.
The Federal Reserve also made clear that the Bank Term Funding Program stopped making new loans after March 11, with the discount window remaining available for liquidity needs. That detail matters because it reinforces the broader point: special facilities can buy time, but the standing backstop remains collateralized borrowing through the central bank. Borrowing is a bridge, not a magic trick.
What Does “Running Out Of Money” Mean When Money Is Mostly Digital?
When people say a bank “ran out of money,” they usually do not mean a literal absence of numbers on screens. They mean the bank no longer has enough immediately usable funds to settle withdrawal requests and payment obligations as they come due. In a digital system, that still comes down to liquid resources and settlement capacity.
Your deposit is a liability of the bank. The bank owes you that amount on demand, but it has used much of the matching asset side for loans and investments. When you transfer funds out, the bank must settle that payment using reserves, cash balances, or funding it can raise quickly. If too many depositors demand transfers at once, the bank can hit a funding wall long before the underlying loan book has stopped being valuable.
This also clears up another common misunderstanding: banks can create deposit money through lending, but that does not mean they can invent emergency liquidity in the middle of a run. Deposit creation and payment settlement are connected, not identical. To meet outflows, the bank still needs reserves, cash, market funding, or central bank credit against collateral. You cannot wire “future asset value” to a depositor who wants money now.
So when a bank runs short, the money did not vanish into thin air. What vanished was the bank’s ability to turn a time-based asset book into same-day payments fast enough and at an acceptable cost. That is a liquidity event, plain and simple.
What Stops Every Bank Run From Becoming A Systemwide Crisis?
Three things usually keep a localized problem from turning into a broader panic: deposit insurance, lender-of-last-resort support, and confidence that supervisors will move fast enough to contain spillovers. Remove those backstops and the incentive to run rises sharply. Keep them credible and many depositors stay put.
Deposit insurance is the first line of defense for ordinary savers. When people know insured deposits are protected, they are less likely to join a panic. The Richmond Federal Reserve notes that deposit insurance was designed to eliminate the need for depositors to run. It does not solve every problem, and it creates its own tradeoffs, but it remains one of the main reasons classic retail bank runs are less common than they once were.
The second line is central bank liquidity support. The discount window exists so generally sound institutions can borrow against collateral and meet short-term funding needs. That keeps a liquidity shortage from immediately forcing destructive asset sales. It is not a blank check, yet it is a vital pressure valve.
The third line is speed in communication and action. In a modern run, hesitation is expensive. Markets, depositors, corporate finance teams, and treasury desks react within hours. If authorities want to stop contagion, they need the message, the backstop, and the operating mechanics lined up before panic snowballs.
What Should You Watch If You Want To Judge Bank Liquidity Risk More Realistically?
Start with deposit composition, not just total deposit size. A bank with a large base of insured consumer deposits usually behaves differently from one funded by concentrated business accounts or sector-specific clients. Uninsured deposits can be useful and profitable, but they are quicker to move. If you ignore that, you miss the main pressure point.
Then look at asset liquidity and mark-to-market sensitivity. Treasury securities and agency holdings are easier to convert than a book of specialized loans, but duration risk still matters. If rising rates leave a bank sitting on large unrealized losses, its options narrow in a stress event. Held-to-maturity accounting may delay recognition, but it does not repeal economic reality when the bank needs cash today.
You should also pay attention to contingent funding plans. Does the bank have borrowing lines ready? Has it pre-positioned collateral? Does it have operational readiness at the discount window? How much collateral is unencumbered? These details sound technical until a run starts. Then they become the difference between a rough week and a closure order.
Last, measure speed. In earlier decades, analysts often had more time to interpret signals. Today, mobile banking, online treasury systems, and social amplification compress the timeline. Liquidity risk is no longer just about how much buffer a bank carries. It is about whether that buffer is big enough for the pace of outflows the bank could face.
Why Do Banks Run Out Of Cash First?
- Banks fund long-term assets with deposits payable on demand.
- Loans and securities may hold value, but they can’t always be sold fast at full price.
- When withdrawals outrun liquid funds, a bank becomes illiquid before it becomes insolvent.
- Forced asset sales can turn a cash squeeze into a capital problem.
Take This Lens With You The Next Time A Bank Panic Hits The Headlines
If you remember one thing, make it this: banks do not fail only when assets disappear, they fail when time runs out. A bank can look solvent in a broad sense and still break if depositors demand cash faster than loans mature, securities can be sold, or collateralized funding can be raised. Once you see that split between asset value and immediate liquidity, headlines about bank stress become a lot easier to read. You’ll also spot why uninsured deposits, funding concentration, interest-rate exposure, and central bank access matter so much. Keep that lens, and you’ll judge banking risk with far more accuracy than the usual “the bank had money on paper” argument allows.
References:
- https://www.richmondfed.org/publications/research/economic_brief/2018/eb_18-03
- https://www.richmondfed.org/publications/research/economic_brief/2026/eb_26-12
- https://www.federalreserve.gov/monetarypolicy/reservereq.htm
- https://www.congress.gov/crs-product/IF10208
- https://www.federalreserve.gov/monetarypolicy/discountrate.htm
- https://www.federalreserve.gov/newsevents/pressreleases/monetary20240124a.htm
- https://www.fdic.gov/consumer-resource-center/deposit-insurance-glance
- https://www.spglobal.com/market-intelligence/en/news-insights/articles/2023/3/svb-signature-racked-up-some-high-rates-of-uninsured-deposits-74747639
- https://www.cnbc.com/2023/03/28/svb-customers-tried-to-pull-nearly-all-deposits-in-two-days-barr-says.html

Olivier Gillier is a global investment strategist and co-founder of RioBlanco Capital LLC, with over 20 years of experience in wealth management and international markets. A former Senior Vice President at Merrill Lynch, he now focuses on private equity, cross-border finance, and philanthropic initiatives worldwide.